Key Takeaways Click to Expand
- Property values can fall as well as rise.
- Rental income can be disrupted by voids, arrears and tenant problems.
- Borrowing increases exposure to interest rate and cash flow risk.
- Regulatory and compliance requirements can create additional costs.
- Maintenance and management responsibilities can affect investment performance.
- Property is relatively illiquid, making a quick sale difficult.
- Due diligence, conservative assumptions and adequate financial reserves can reduce exposure to these risks.
Property investment can provide rental income and potential long-term capital growth, but it also exposes investors to risks that can affect income, property values, cash flow and the ability to exit an investment.
The main risks include changes in property values, rental voids, tenant problems, borrowing costs, regulatory requirements, maintenance expenses and limited liquidity.
Understanding these risks before committing capital allows investors to assess whether a particular property remains viable when conditions are less favourable.
For the broader context of investing in UK property, see our guide to UK property investment.
Table of Contents
Table of Contents
What are the main risks of property investment
UK property investment risk can be grouped into several areas:
Risk | What can happen |
|---|---|
Market risk | Property values fall or demand weakens |
Rental risk | Voids, arrears or tenant problems reduce income |
Financial risk | Interest rates or borrowing costs increase |
Regulatory risk | Rules or compliance requirements change |
Operational risk | Repairs and management costs increase |
Liquidity risk | Selling takes longer or requires a price reduction |
Local market risk | Weak demand affects occupancy or resale |
These risks can interact. For example, falling property values combined with high borrowing can weaken an investor’s equity position, while a prolonged void can make mortgage and property costs harder to meet.
Market and property value risk
Property prices are not guaranteed to increase. Economic conditions, mortgage affordability, employment, housing supply and buyer demand can all affect property values.
The UK market can also behave differently between regions and property types. HM Land Registry’s June 2026 data reported an average UK house price of £272,000 and annual price growth of 2.0 percent. Regional performance varied considerably, with the North West recording 4.7 percent annual growth while London recorded a 2.5 percent annual fall.
The latest UK House Price Index data from HM Land Registry therefore illustrates why national house price growth should not be assumed to apply equally to every property.
Market risk is particularly relevant when an investment depends on continued price growth to support its expected outcome. A property should remain financially viable even if capital growth is slower than expected or property values temporarily decline.
Tenant and rental income risk
Rental income can be affected by more than the headline rent.
Potential problems include:
- Rental arrears.
- Tenant turnover.
- Extended void periods.
- Property damage.
- Disputes.
- Unexpected letting costs.
- Weaker local rental demand.
A property that appears attractive based on its expected rent may therefore perform differently once periods without income and the costs of maintaining the tenancy are considered.
Rental demand should be assessed using evidence from the relevant market rather than assuming that a property will remain occupied continuously.
What is void risk in property investment
A void occurs when a property is vacant and not generating rental income.
During a void period, the investor may still have to meet costs such as:
- Mortgage payments.
- Insurance.
- Service charges.
- Maintenance.
- Council tax where applicable.
- Utility standing charges.
The financial impact depends on the property’s costs, available reserves and the length of the vacancy.
Void risk can be higher where rental demand is weak, competing properties are abundant, the property is poorly maintained or the asking rent is above what tenants are willing to pay.
The important question is whether the investment can withstand a reasonable period without rental income.
Financial and interest rate risk
Borrowing can increase an investor’s exposure to financial risk because mortgage obligations continue even when rental income or property values fall.
Interest rate changes can affect:
- Mortgage payments.
- Monthly cash flow.
- Refinancing costs.
- Affordability.
- The amount an investor can borrow.
The Bank of England maintained Bank Rate at 3.75 percent in July 2026. Changes in monetary policy can affect borrowing conditions, so investors should assess affordability under less favourable financing conditions rather than relying only on the rate available at purchase.
The Bank of England’s July 2026 monetary policy decision provides the relevant current policy context.
Cash flow risk
Cash flow risk arises when property income is insufficient to cover ongoing costs.
Relevant costs can include mortgage payments, insurance, maintenance, management fees, service charges and periods without rent.
An investment can therefore become financially difficult even when it continues generating rental income.
Stress-testing the investment against lower rental income, higher costs or increased borrowing costs can show whether there is sufficient financial resilience.
Negative equity risk
Negative equity occurs when a property’s market value falls below the amount outstanding on the mortgage.
A significant fall in property value can leave an investor owing more than the property could currently sell for.
Negative equity can make refinancing or selling more difficult and may require the investor to provide additional funds to complete a sale.
The risk is generally greater where an investment has high leverage and limited equity.
Regulatory and compliance risk
Property investors must comply with rules affecting how a property is owned, financed, let and managed.
Regulatory risks can include changes to:
- Landlord and tenant requirements.
- Licensing.
- Energy efficiency standards.
- Safety requirements.
- Tax rules.
- Mortgage regulation.
- Local authority requirements.
These changes can create additional costs or affect how an investment can be operated.
Investors should verify the requirements that apply to a particular property rather than relying on assumptions based on another property or another local authority.
Taxation risk
Tax rules can affect the financial position of a property investment. The applicable treatment depends on factors including ownership structure, rental income, allowable expenses and the investor’s circumstances.
Investors should establish the tax treatment relevant to their situation rather than relying on general assumptions. HMRC’s guidance on working out rental income from property explains how rental income, allowable expenses and taxable profit are treated.
This article does not attempt to provide detailed tax planning.
Energy efficiency risk
Energy efficiency requirements can create additional expenditure where a property needs improvements to meet applicable requirements.
For domestic private rented property in England and Wales, the current Minimum Energy Efficiency Standards require qualifying properties to meet the applicable requirements, subject to relevant exemptions. The current government guidance was updated in May 2026.
Investors assessing a rental property should therefore check the applicable requirements using the GOV.UK landlord guidance on minimum energy efficiency standards.
Operational and maintenance risk
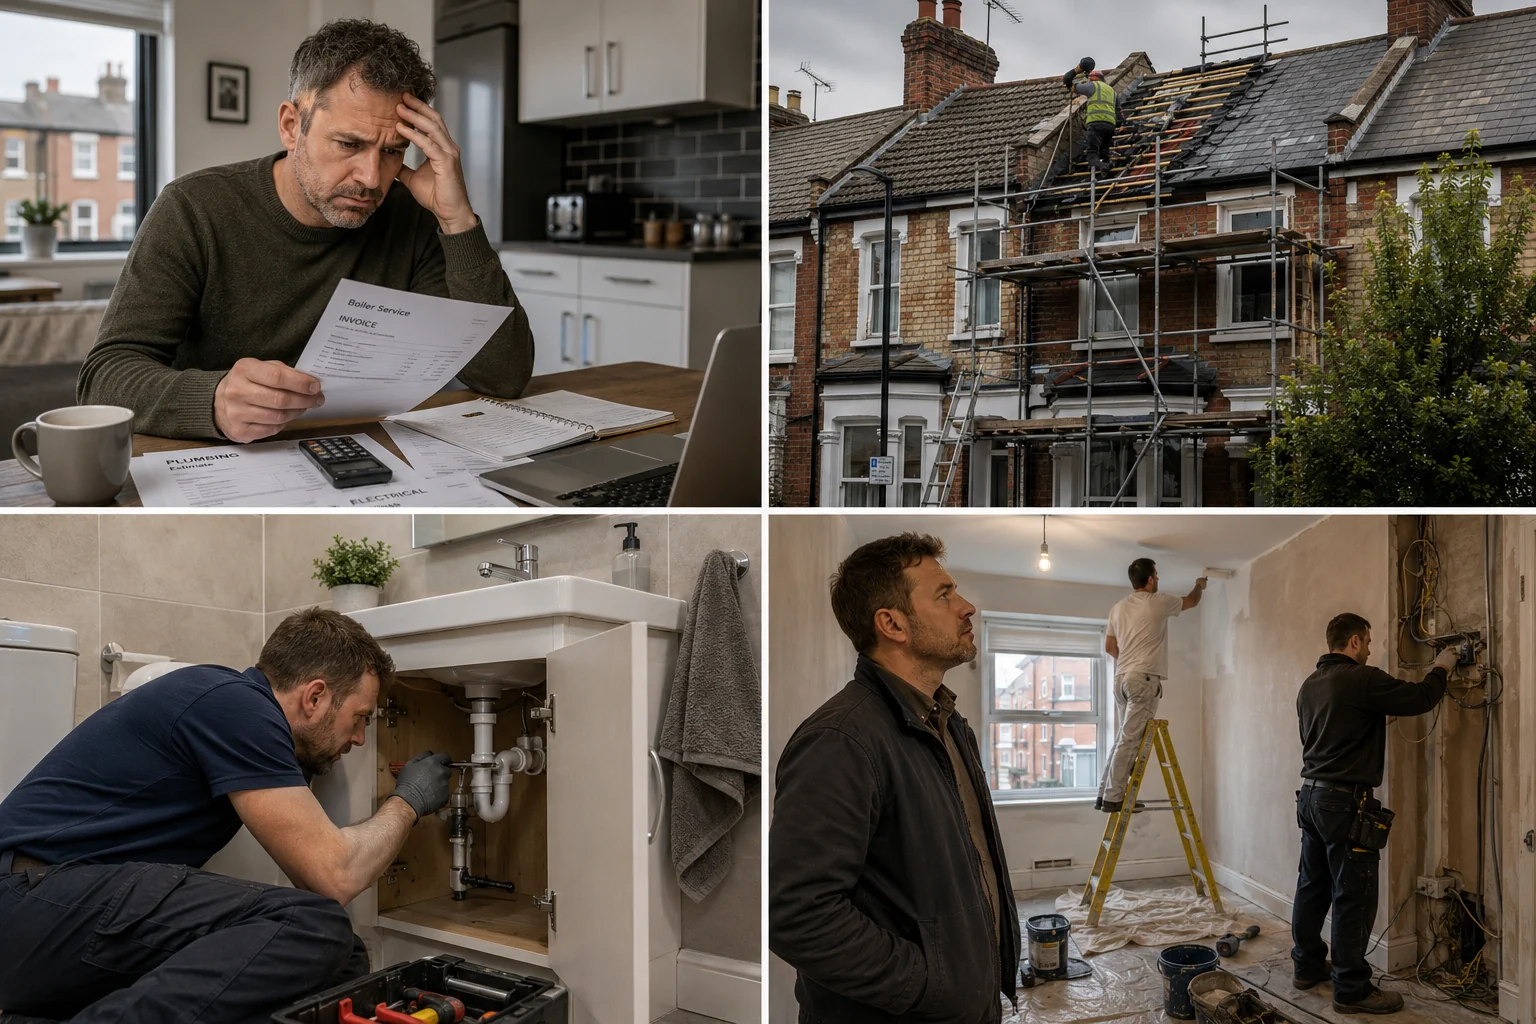
Property is a physical asset, so ownership creates ongoing maintenance responsibilities.
Unexpected costs can arise from:
- Heating systems.
- Plumbing.
- Electrical work.
- Roofing.
- Damp.
- Structural defects.
- General repairs.
- Replacement of fixtures and fittings.
A survey can identify many potential problems before purchase, but it cannot eliminate the possibility of future expenditure.
Maintenance risk is therefore partly a question of financial resilience. An investment with no allowance for unexpected repairs can become difficult to manage when a major expense occurs.
Management also creates an operational burden. Investors who manage properties themselves may need to deal with tenants, repairs, rent collection, inspections and compliance. Using a management service can reduce the workload, but introduces an additional cost.
Liquidity and forced-sale risk
Property is relatively illiquid. Unlike a listed security, it cannot normally be sold immediately when an investor needs access to capital.
A property sale can involve:
- Finding a buyer.
- Agreeing a price.
- Conveyancing.
- Surveys.
- Mortgage arrangements.
- Completion.
Weak market conditions can make the process slower and may reduce the price buyers are willing to pay.
What is forced-sale risk
Forced-sale risk occurs when an investor needs to sell because of financial pressure or an urgent need for capital.
Selling under pressure can reduce the investor’s negotiating position. If the market is weak, the property may need to be sold below its expected value, potentially crystallising a loss.
Maintaining appropriate cash reserves can reduce the likelihood that an investor has to sell solely because of a short-term financial problem.
Geographic and local market risk
Property investment risk is also influenced by the local market in which the property is located.
Local risks can include:
- Weak employment.
- Falling population.
- Reduced rental demand.
- Excess property supply.
- Changes in local infrastructure.
- Dependence on a limited number of economic sectors.
National property statistics cannot fully describe the risk of an individual property. Investors should consider local evidence such as comparable rents, vacancy conditions, transaction activity and demand for similar properties.
The objective is not to predict exactly what a local market will do. It is to identify factors that could weaken demand, income or resale prospects.
How can investors reduce property investment risks
Risk cannot be eliminated, but investors can reduce unnecessary exposure by testing an investment against realistic adverse conditions.
Conduct thorough due diligence
Due diligence should establish whether the property, local market and financial assumptions support the proposed investment.
This can include reviewing:
- Comparable property prices.
- Comparable rental evidence.
- Local rental demand.
- Property condition.
- Compliance requirements.
- Ongoing property costs.
- Financing assumptions.
Headline rental figures or projected growth should not be treated as sufficient evidence on their own.
For the separate question of selecting an appropriate investment, see our guide to choosing the right property investment.
Use conservative financial assumptions
Investors should consider how the investment performs if conditions are less favourable.
Useful stress tests can include:
- Higher mortgage costs.
- Lower rental income.
- Longer void periods.
- Higher maintenance costs.
- Lower property values.
The purpose is not to predict the worst possible outcome. It is to determine whether the investment has enough financial resilience to withstand reasonable changes in conditions.
Maintain adequate financial reserves
Cash reserves can provide protection against temporary problems such as a void, unexpected repair or increased borrowing cost.
An investor who has no financial buffer may have fewer options when conditions deteriorate.
Avoid excessive concentration
Concentration can increase risk when too much capital depends on one property, one local market or one source of rental demand.
Diversification can reduce concentration risk, although it does not remove the underlying risks associated with property investment.
How should investors assess property investment risk
A useful risk assessment should consider both the likelihood of a problem and its potential financial impact.
Before investing, ask:
- What could cause the property’s income to fall?
- What could cause its costs to increase?
- What could cause its value to decline?
- How would the investment perform during a prolonged void?
- What happens if borrowing costs increase?
- What would happen if the property needed to be sold earlier than planned?
- Are there regulatory or compliance costs that have not been included?
- Is there enough financial capacity to absorb unexpected costs?
The answers provide a more useful assessment of risk than relying on a single yield, forecast or expected capital growth figure.
For the separate question of how investment performance is generated and measured, see our guide to UK property investment returns.
Conclusion
UK property investment involves several interconnected risks. Property values can fall, rental income can be interrupted, borrowing costs can increase, regulations can change and unexpected property costs can arise.
The objective is not to eliminate every risk. It is to identify the material risks before investing, test the investment against less favourable conditions and ensure there is sufficient financial resilience to manage them.
A property investment should therefore be assessed on more than its expected rent or potential capital growth. The underlying property, local demand, costs, financing, compliance requirements and exit options all need to withstand reasonable changes in conditions.
Frequently Asked Questions
- What makes property investment riskier than expected?
Property investment can be riskier than expected when rental income, property values or costs differ from the investor’s assumptions. Common causes include unexpected maintenance costs, rental voids, tenant problems, higher borrowing costs, regulatory changes and weaker local demand.
- What is void risk in property investment?
Void risk is the risk of a property remaining vacant between tenancies, resulting in lost rental income. The investor may still need to cover mortgage payments, insurance, maintenance and other costs during the vacancy.
- How does leverage increase property investment risk?
Leverage increases risk because borrowed money creates financial obligations even when property values or rental income fall. Higher borrowing can amplify losses and increase exposure to interest rate changes, particularly when an investment has limited cash reserves.
- What is negative equity risk in property investment?
Negative equity occurs when a property’s market value falls below the outstanding mortgage balance. This can make selling or refinancing more difficult because the investor may need to provide additional funds to repay the mortgage.
- What is forced-sale risk in property investment?
Forced-sale risk occurs when an investor needs to sell a property quickly because of financial pressure or a need for liquidity. If market conditions are weak, the property may have to be sold below its expected value, potentially crystallising a loss.
Disclaimer: This article is for general information only and does not constitute financial, investment, tax or legal advice. Property investment involves risk, and independent professional advice should be sought before investing.